Quantitative Options Articles
5 ArticlesIn-depth educational guides on Black-Scholes financial mathematics, Greeks risk management, and multi-leg spread execution.
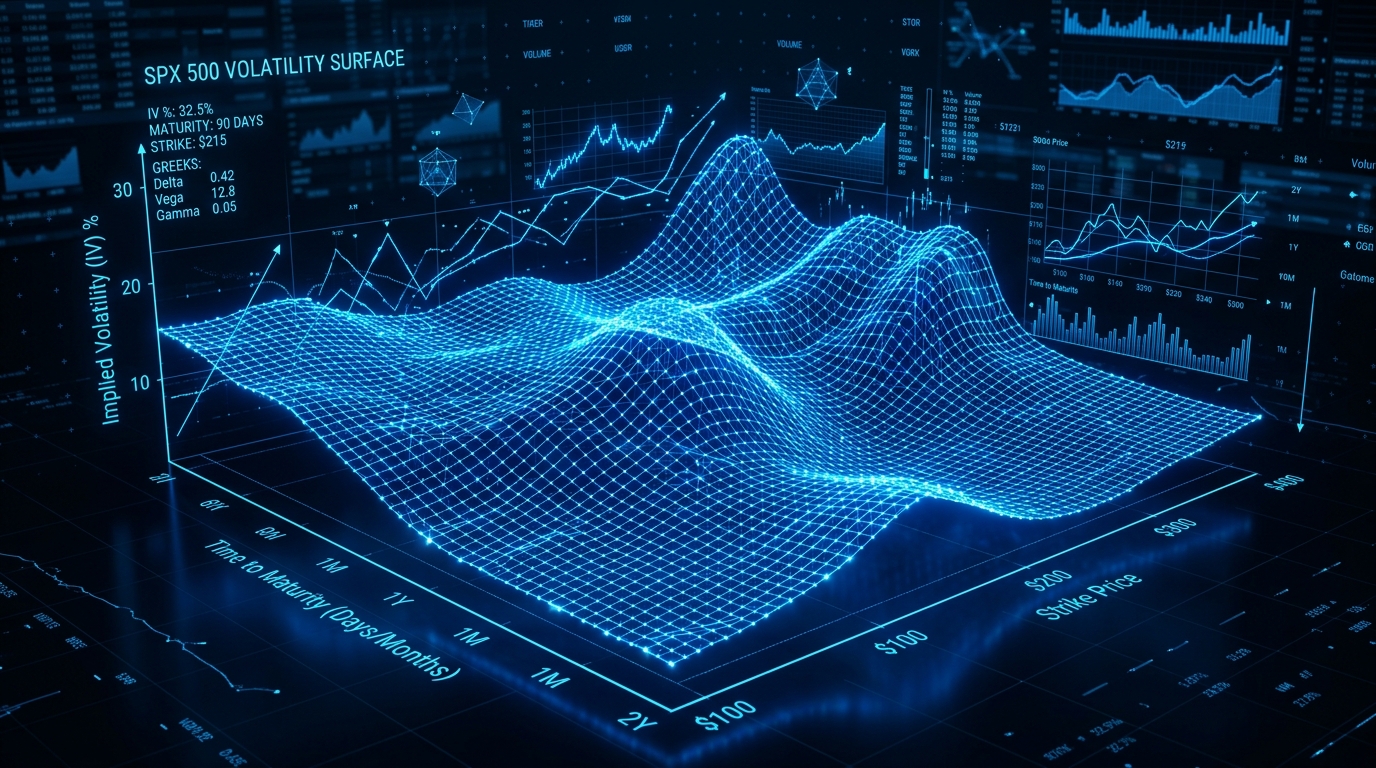
Demystifying Implied Volatility & The Volatility Surface
Learn how implied volatility is reverse-engineered from option prices, why volatility smiles occur, and how to trade IV contraction.
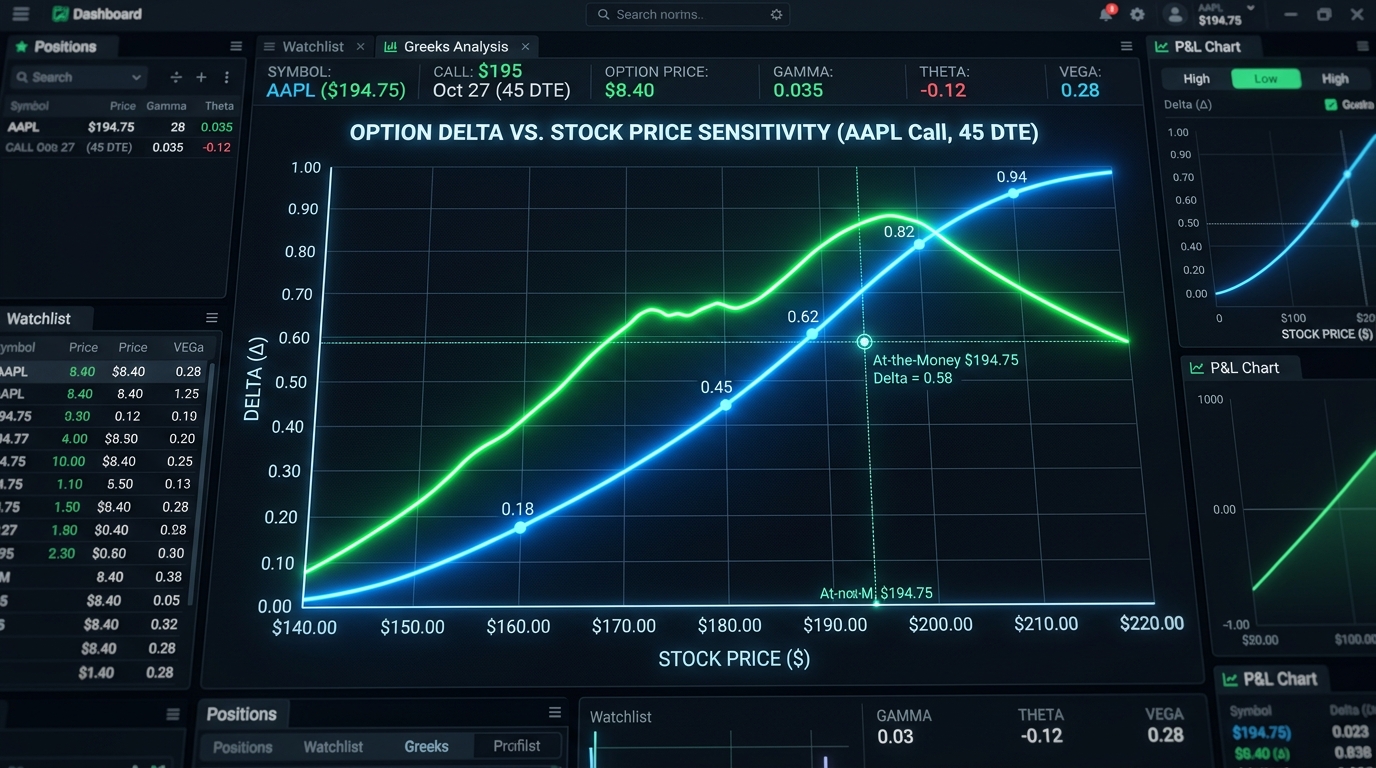 Greeks
Mastering Option Delta & Constructing Delta-Neutral Hedges
A deep dive into Delta as share-equivalency, directional risk, and how institutional market makers balance portfolio delta.
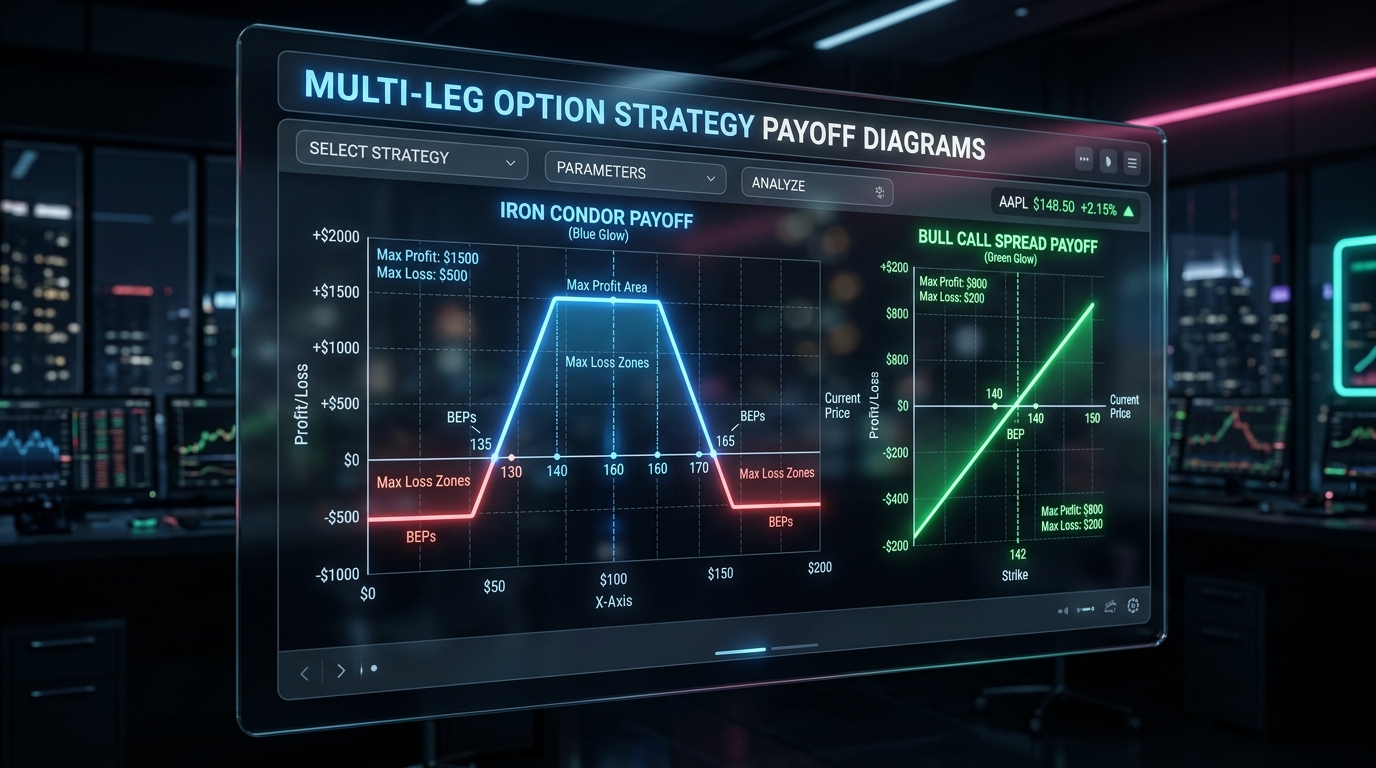 Strategies
Understanding Multi-Leg Option Spreads: Bull Call vs Iron Condor
Compare defined-risk multi-leg strategies to manage risk-reward profiles, maximize probability of profit, and reduce capital outlay.
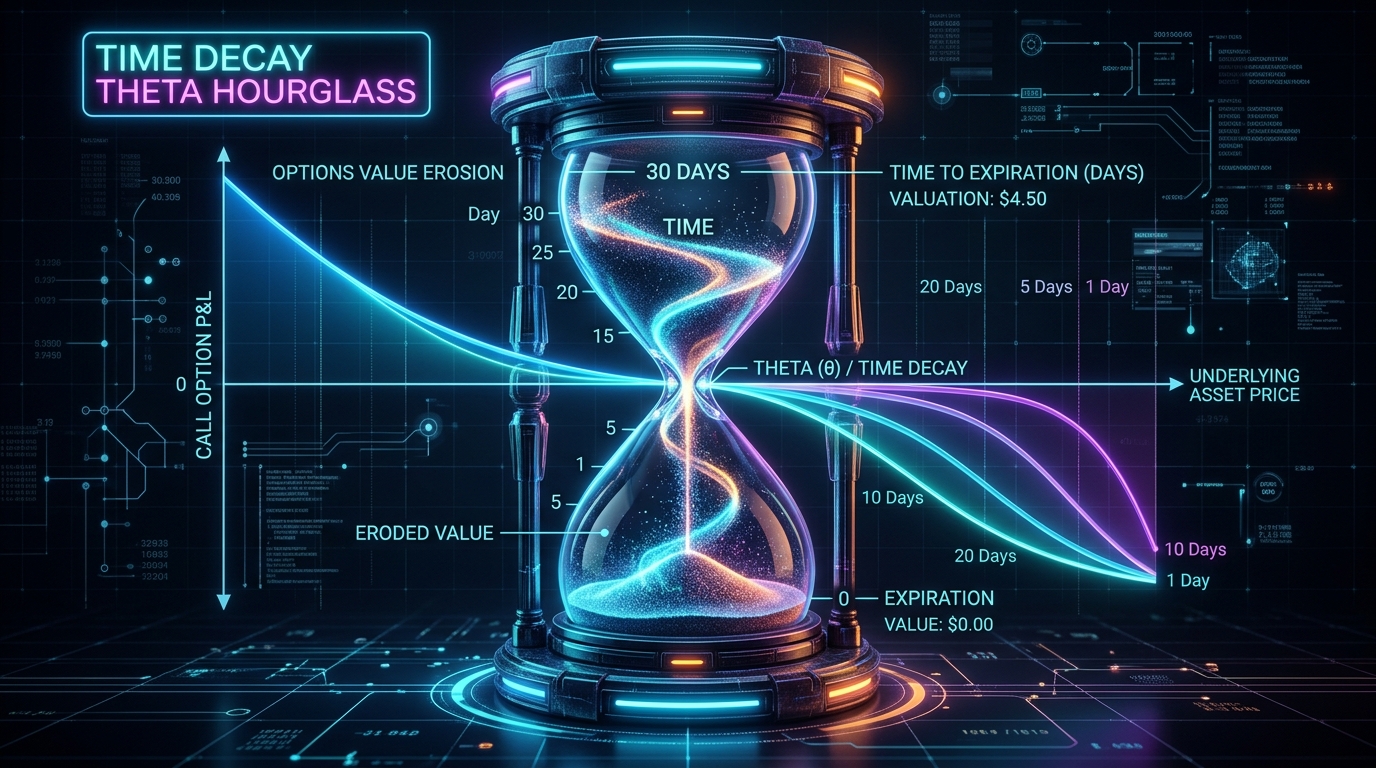 Time Decay
Theta Decay: How Options Value Erodes Over Time
Examine the non-linear acceleration of time decay in the final 30 days before expiration and how options sellers capitalize on Theta.
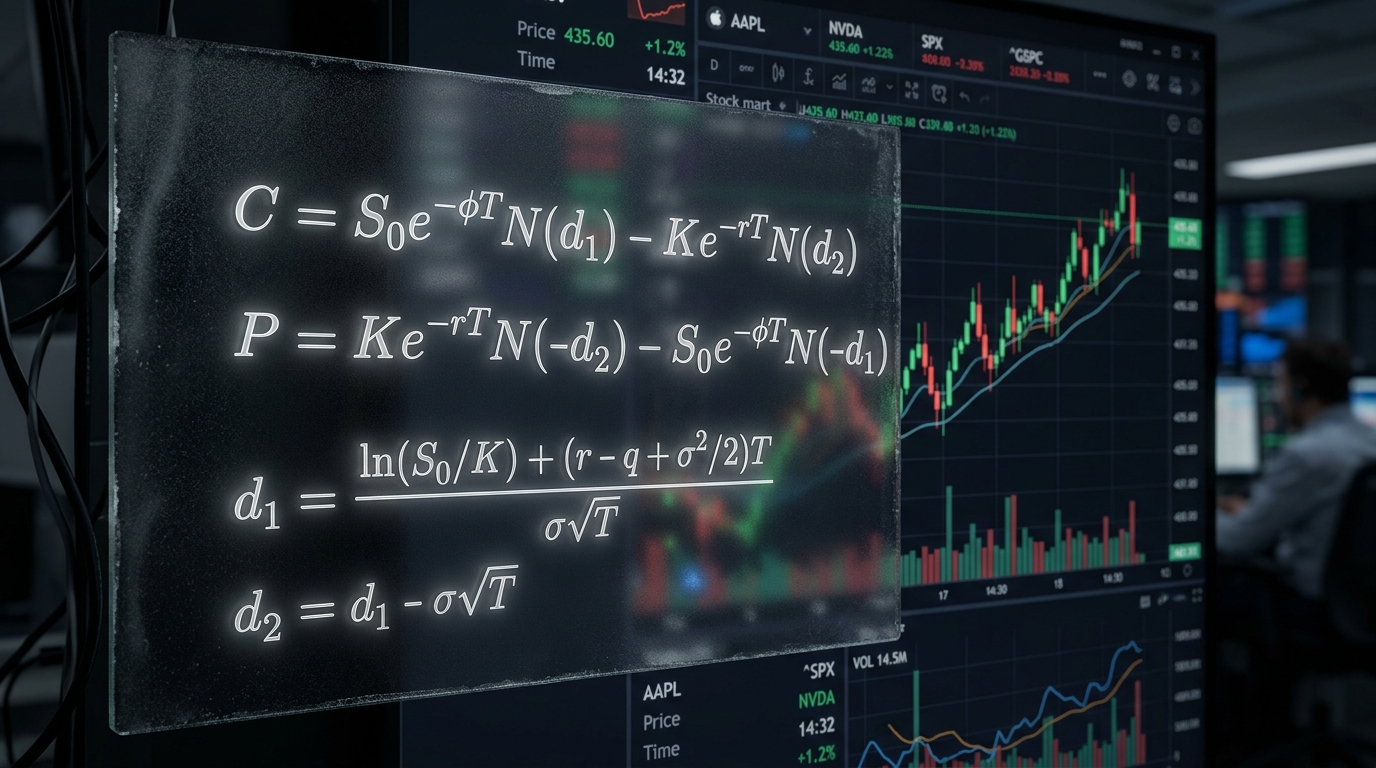 Quantitative Finance
The Black-Scholes Model: Derivations, Assumptions, and Limitations
Understand the mathematical foundations of the 1973 Nobel-prize winning model and why fat tails cause real-world deviations.