Mastering Option Delta & Constructing Delta-Neutral Hedges
A deep dive into Delta as share-equivalency, directional risk, and how institutional market makers balance portfolio delta.
📌 Key Takeaways
- ✓Delta (Δ) measures the expected change in option price for a $1.00 move in the underlying stock.
- ✓Call options have positive Delta (0 to +1.0), while Put options have negative Delta (-1.0 to 0).
- ✓Delta acts as a share-equivalency metric for hedging risk exposure.
- ✓Delta-neutral hedging matches portfolio option Delta with underlying stock shares to eliminate directional risk.
📖 Table of Contents
1. The Three Interpretations of Delta
Option Delta (Δ) is the premier Greek risk metric. Professional trading desks interpret Delta in three complementary ways:
- Price Sensitivity: A call option with a Delta of +0.60 gains $0.60 when the underlying stock rises $1.00.
- Share-Equivalency Ratio: Owning 10 long call contracts (1,000 multiplier) with +0.60 Delta represents the exact directional risk of owning 600 shares of stock.
- Approximate Probability of Expiry: In near-term options, a 0.30 Delta option carries roughly a 30% probability of expiring in-the-money.
2. Delta Behavior Across Strike Prices
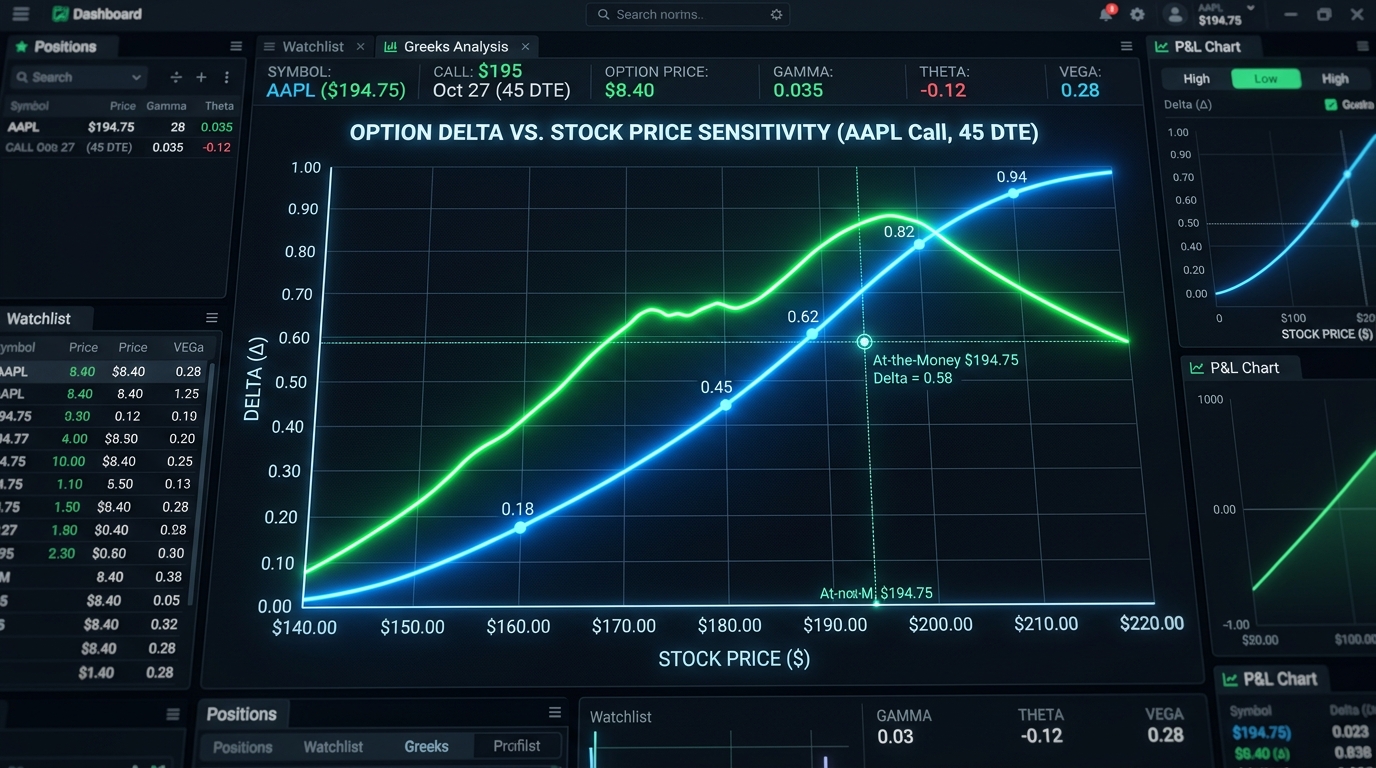
At-the-money (ATM) call options generally have a Delta of approximately +0.50. Deep in-the-money (ITM) calls approach +1.00, behaving like stock shares, while deep out-of-the-money (OTM) calls decay toward 0.00.
3. Constructing Delta-Neutral Portfolios
Market makers profit from bid-ask spreads rather than taking directional stock bets. To eliminate market directional risk, market makers execute stock hedges such that total portfolio Delta equals zero:
4. The Impact of Gamma on Delta Stability
Because underlying stock prices change continuously, Delta itself changes over time. Gamma (Γ) measures how fast Delta moves, requiring periodic dynamic re-hedging to maintain neutrality.
📜 In This Article
Try Option Pricing Tools Live
Calculate Black-Scholes theoretical prices, Greeks, and multi-leg strategy payoffs instantly in your browser.
Open Black-Scholes Pricer →