Demystifying Implied Volatility & The Volatility Surface
Learn how implied volatility is reverse-engineered from option prices, why volatility smiles occur, and how to trade IV contraction.
📌 Key Takeaways
- ✓Implied Volatility (IV) is reverse-calculated from option market prices using root-finding algorithms like Newton-Raphson.
- ✓Unlike historical volatility which looks backward, IV reflects the market's forward-looking expectation of price range.
- ✓Volatility smiles and skews occur because out-of-the-money options carry higher crash risk premiums.
- ✓High IV expands option prices; trading after earnings calls often involves capitalizing on IV collapse (vol crush).
📖 Table of Contents
1. What is Implied Volatility?
Implied Volatility (IV) is the single most critical variable in option pricing. While spot price, strike price, expiration time, and interest rates are directly observable in financial markets, IV is solved in reverse from traded market option premiums using numerical root-finding algorithms.
Expressed as an annualized percentage, higher IV signifies greater expected price fluctuations, resulting in higher option premiums for both calls and puts.
2. Implied Volatility vs Historical Volatility
| Metric | Direction | Primary Source | Use Case |
|---|---|---|---|
| Historical Volatility (HV) | Backward-Looking | Past Stock Return Std Dev | Measuring actual realized movement |
| Implied Volatility (IV) | Forward-Looking | Market Option Premiums | Pricing future market risk & uncertainty |
3. The Volatility Smile & Surface
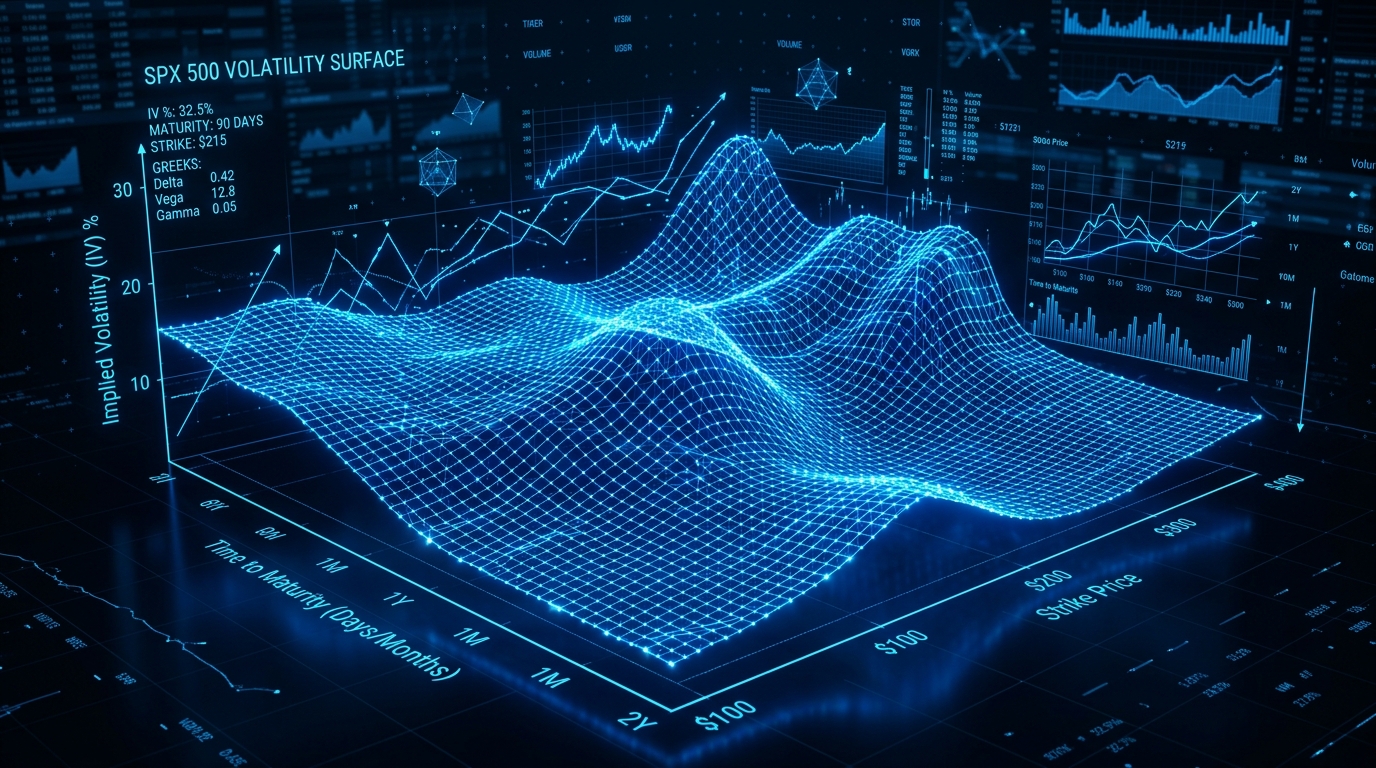
In theoretical Black-Scholes modeling (1973), volatility is assumed constant across all strike prices and expiries. However, empirical market data reveals a distinct volatility smile or volatility skew.
Out-of-the-money put options frequently trade at elevated IVs compared to at-the-money options because institutional investors demand downside tail-risk protection against sudden market selloffs.
4. Mathematical Solution: Newton-Raphson Solver
Because the cumulative normal distribution function inside Black-Scholes cannot be algebraically inverted, software pricing engines calculate IV iteratively:
When Vega approaches zero near deep ITM/OTM extremes, modern solvers switch to bisection binary search methods to guarantee 100% numerical convergence down to 1e-6 precision.
5. Practical Trading Applications
Options traders monitor IV Rank (IVR) and IV Percentile to determine whether options are cheap or expensive:
- High IV Environment: Sell premium via Iron Condors, Credit Spreads, or Covered Calls.
- Low IV Environment: Buy premium via Long Straddles or Debit Spreads.
📜 In This Article
Try Option Pricing Tools Live
Calculate Black-Scholes theoretical prices, Greeks, and multi-leg strategy payoffs instantly in your browser.
Open Black-Scholes Pricer →