Time Decay
Theta Decay: How Options Value Erodes Over Time
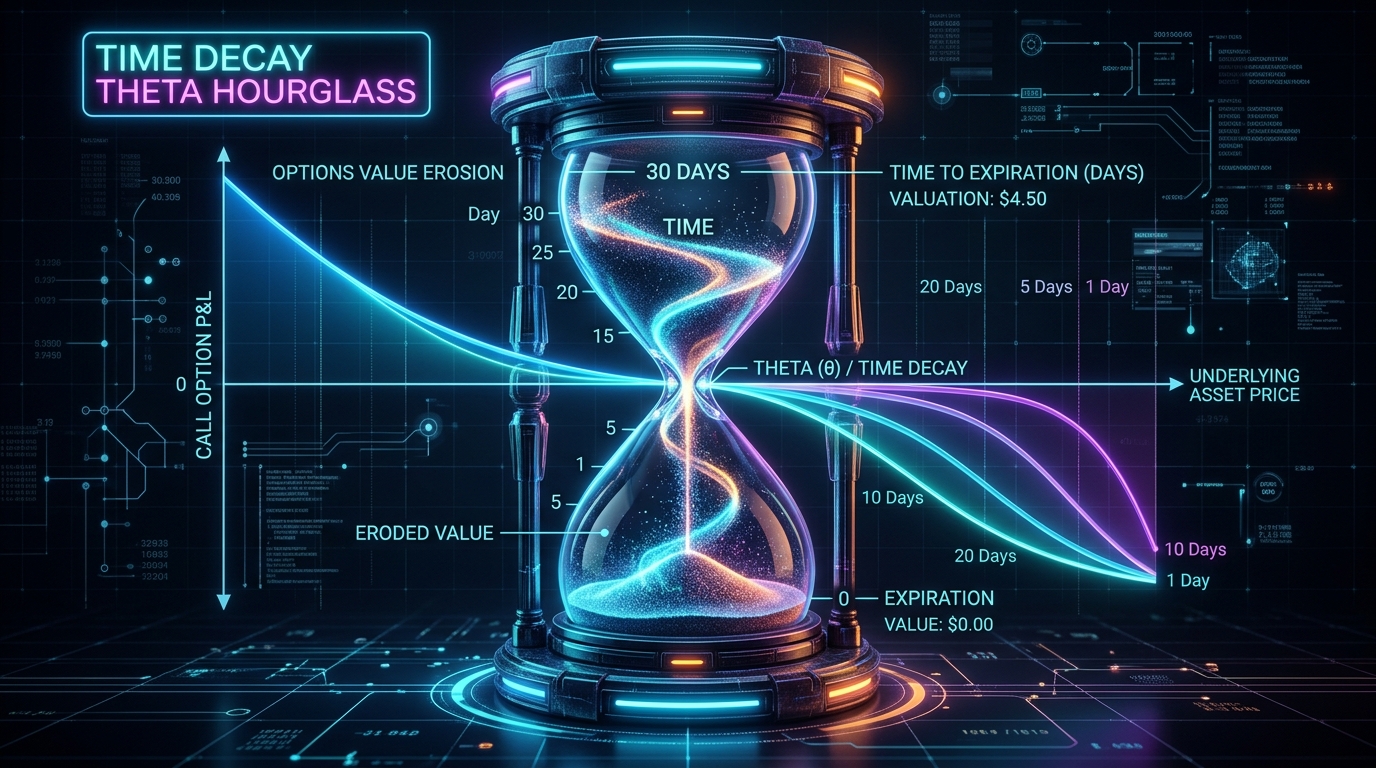
Examine the non-linear acceleration of time decay in the final 30 days before expiration and how options sellers capitalize on Theta.
📅 28 August 2026•⏱️ 5 min read•✍️ OptionPricing Quantitative Team
Share:
📢 Share this Quantitative Guide:
📌 Key Takeaways
- ✓Theta (Θ) quantifies the dollar erosion of an option price per calendar day.
- ✓Time decay is non-linear and accelerates sharply inside the final 30-45 days to expiry.
- ✓At-the-money (ATM) options experience the highest absolute Theta decay.
- ✓Option sellers harvest Theta decay as positive daily cash flow.
📖 Table of Contents
1. Understanding Theta Decay
Options are wasting assets. As time passes toward expiration, the extrinsic (time value) component of an option's premium decays continuously.
2. The Non-Linear Decay Curve
Theta decay is non-linear. An option with 90 days remaining erodes slowly, but experiences rapid exponential decay during the final 30 to 45 days before expiration.
3. Option Buyers vs Option Sellers
Option buyers fight negative Theta decay every calendar day. Net option sellers (credit spread and covered call traders) profit directly from Theta erosion as time passes.
Found this quantitative guide helpful?Share it with fellow option traders and financial analysts.
📜 In This Article
Try Option Pricing Tools Live
Calculate Black-Scholes theoretical prices, Greeks, and multi-leg strategy payoffs instantly in your browser.
Open Black-Scholes Pricer →